CTGDF's Net Profit Rose 19.9% — So Why Is Its Profitability Nothing to Celebrate?
2026-07-16 7:46 AMChina
Overview
China Tourism Group Duty Free Corporation (CTGDF), the world's largest duty-free operator, reported H1 2026 net profit up 19.9% year-on-year. But revenue actually declined, and pre-tax profit fell 20%. Goldman Sachs is blunt about it: the net profit gain is "entirely" a tax effect. This piece unpacks the Hainan voucher dependency hiding behind the headline number, and what Korea's duty-free industry should take from it.
China Tourism Group Duty Free Corporation (CTGDF), the world's largest duty-free operator, released preliminary H1 2026 results (period ended June 30) on July 14, and the headline looks impressive: net profit up 19.9% year-on-year. Yet in the same release, revenue fell 1.99%. A company whose revenue declined while its net profit jumped nearly 20% is, on its face, an odd combination. Goldman Sachs Research called the release a possible "positive surprise" for the market — before immediately correcting the record: the net profit increase was "entirely due to lower tax expenses and a smaller minority interest deduction," and had nothing to do with operational improvement.
The Raw Numbers — H1 by the Figures
CTGDF's disclosed preliminary results are as follows (unit: RMB 10,000).
Metric
Current Period (H1 2026)
Prior Year
YoY Change (%)
Total Revenue
2,759,172.27
2,815,075.00
-1.99
Operating Profit
374,154.25
370,798.85
0.90
Total Profit
374,454.96
366,347.92
2.21
Net Profit Attributable to Owners
310,648.47
259,975.29
19.49
Net Profit Attributable to Owners (excl. non-recurring items)
307,976.45
259,532.96
18.67
Basic EPS (RMB)
1.4983
1.2566
19.23
Weighted Average ROE (%)
5.46
4.65
+0.81pp
Converted, that's CNY 27.59 billion (about US$4.07 billion) in total revenue and CNY 3.10 billion (about US$458 million) in net profit attributable to owners. Taken at face value, operating profit (+0.90%) and total profit (+2.21%) are both modestly positive too. The problem is that these numbers tell a completely different story once you break them down by quarter.
The Core Insight — Pre-Tax Profit Down 20%, Net Profit Up Anyway
The crack Goldman Sachs identified starts at earnings before tax (EBT). Q2 2026 EBT came in at RMB 948 million, down 20% year-on-year, with margin falling to 8.9% from 10.4% in Q2 of the prior year — a 1.6-percentage-point drop. Group revenue growth itself turned negative in Q2, at -6% (versus +1% in Q1). In other words, actual operating performance is clearly deteriorating, while lower tax expenses and a shrinking minority-interest deduction more than offset that at the bottom line. Judging the company's performance from the H1 headline number (+19.9%) alone leads to essentially the opposite conclusion from reality.
The crack becomes even clearer by segment. Hainan offshore duty-free revenue grew 5% YoY in Q2 (RMB 6.0 billion, about US$886 million) — a sharp deceleration compared with Q4 2025 (+19%) and Q1 2026 (+28%). Goldman Sachs describes this as "normalization following the fade-out of government voucher effects." The airport and online channels fell 18% YoY — an improvement from Q1's decline (-38%, per Goldman Sachs estimates) but still firmly negative, even after factoring in the addition of Hong Kong/Macau DFS acquisition revenue.
Gross margin, at least, held up: 33.9%, a modest improvement from Q1's 33.6%. The company attributed this to "pricing discipline that avoided excessive discounting during the April–June off-season" — choosing to protect margin rather than compete on discounts. Per-capita airport spending also stabilized at RMB 80–150 (US$11.50–22.16), halting a multi-quarter decline for the first time. That stabilization, though, came alongside a slowdown in international passenger growth itself (+6% YoY in Q2, versus +13% in Q1 and +17% in Q4 2025). A 30–40% year-on-year jump in airfares in May–June, driven by fuel surcharges tied to the Middle East conflict, is also cited as a factor behind the traffic slowdown.
The Next Quarter Comes Down to Whether the Vouchers Return
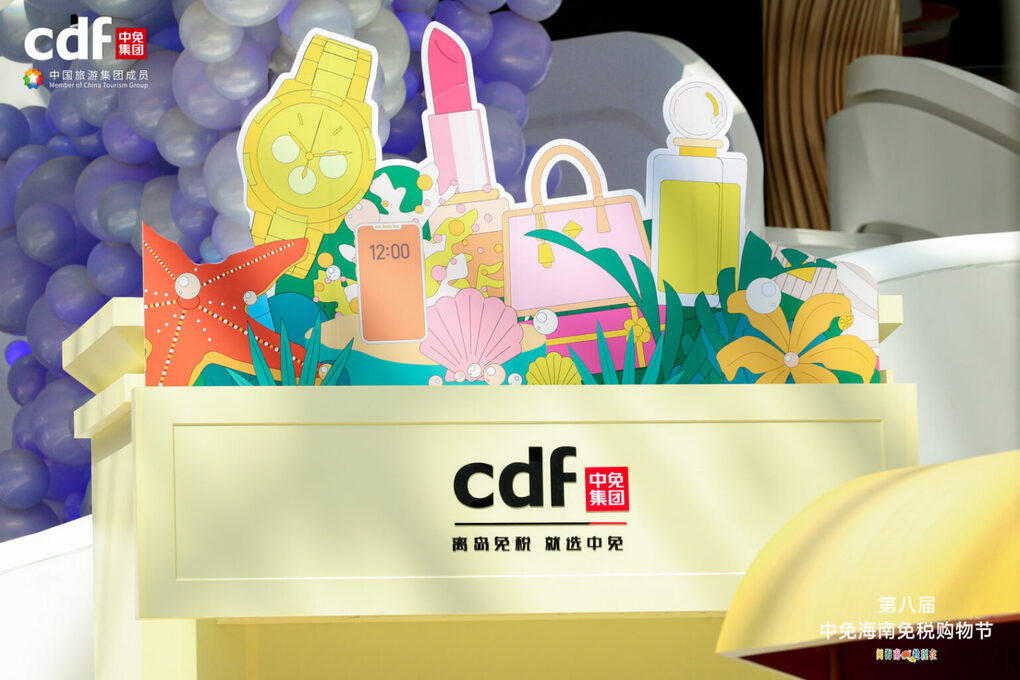
In its disclosure, CTGDF credited itself with "continuing to solidify its competitive advantage in the Hainan market by fully leveraging opportunities from the Hainan Free Trade Port's special whole-island customs clearance policy and new offshore duty-free policies." The company is indeed pushing hard on H2 demand: from July 10 through August 31, it's running the "5th Hainan International Offshore Duty-Free Shopping Festival" and the "8th cdf Hainan Offshore Duty-Free Shopping Festival" simultaneously across six Hainan stores, spanning 47 duty-free categories and more than 1,000 participating brands.
The '5th Hainan International Offshore Duty-Free Shopping Festival' at the cdf Haikou International Duty-Free Shopping Complex — a large-scale consumption drive aimed at an H2 rebound amid slowing earnings
Goldman Sachs, however, remains cautious. It cut its Hainan offshore duty-free revenue growth forecast from +20% to +15%, and is assuming +10% YoY growth for H2. Its verdict was blunt: "H2 26 duty-free sales momentum ultimately depends on whether the Hainan government issues another round of cash vouchers, as it did late last year and early this year." With consumer sentiment weak, the pillar propping up performance isn't product strength or brand competitiveness — it's government fiscal support. The company itself expects some relief once planned renovations of mainland China airport stores are completed by year-end.
What Korea's Duty-Free Industry Should Take From This
CTGDF competes directly with Lotte and Shilla in the global duty-free market as the dominant No. 1 player. Even a company of that scale exposing a structural weakness — that "growth halves the moment the vouchers stop" — carries two lessons for Korea's industry.
First, the trap of headline numbers. Korean duty-free operators, too, often lead their quarterly earnings releases with net profit improvement, and CTGDF's case shows exactly why it matters to distinguish whether that improvement comes from a genuine operating recovery or from one-off cost reductions and tax effects. Second, the double edge of the Hainan model. Hainan has already proven that a large government-driven duty-free zone can lift consumption sharply in the short term — but it has just as clearly shown that sustaining that growth ultimately depends on continued policy support. As Korea debates expanding duty-free allowances or easing regulations, this is a useful reference case for separating "one-time stimulus" from "structural demand recovery" in policy design.
This gap also leaves a practical homework assignment worth noting. For Korean duty-free operators, taking a cue from CTGDF's gap between -20% EBT and +19.9% net profit, disclosing pre-tax and operating profit trends alongside net profit in quarterly releases would help manage investor trust. For policy makers, there's a different lesson: Hainan's voucher-dependent growth model is effective at short-term stimulus, but keeps repeating a pattern where growth plunges sharply the moment vouchers expire — so any redesign of Korea's duty-free system (easing exchange restrictions, adjusting allowances, and the like) should factor in this kind of "policy cliff" risk from the design stage. For analysts and investment teams, when treating CTGDF's results as a bellwether for the broader China travel retail sector, it makes sense to track Hainan offshore duty-free (now normalizing) and the airport/online channels (still negative) separately, since the two are recovering at clearly different speeds. For airport duty-free brands, this is a period where slowing growth in Chinese outbound international passenger traffic (+6% YoY) is coinciding with a spike in airfares, so stores heavily dependent on China-origin traffic need to build more conservative, passenger-count-based H2 sales plans.
CTGDF's H1 results tell an entirely different story depending on how far you dig. At the headline level, it's a growing company; at the pre-tax profit level, it's a company under pressure. The gap between the two makes something clear: accounting-level net profit improvement and genuine operating recovery are two different questions, and even the world's largest duty-free zone can't sustain double-digit growth on its own, without government vouchers. H2 results will ultimately hinge on Hainan's fiscal decisions.
✦RIT's Insights
The number most worth watching in this earnings report isn't +19.9% — it's -20%. A 20% drop in pre-tax profit alongside a nearly 20% rise in net profit means there's an accounting buffer — tax effects, a shrinking minority-interest deduction — sitting between the company's underlying operating strength and its final reported number. This kind of illusion isn't unique to CTGDF; it's a common temptation for any large retailer whose growth is slowing.
That's exactly where RIT got stuck on first reading this table. Korean duty-free operators also tend to lead with net profit metrics every earnings season, and investors and partner companies need to make a habit of checking operating profit and pre-tax profit trends alongside it. Judging a company's health from a single headline number is dangerous, as this CTGDF case shows precisely. Hainan's voucher dependency should be read as having already entered its second slowdown cycle — if growth keeps halving every time government support stops, that pattern isn't a temporary adjustment; it needs to be treated as a structural limitation of the Hainan model itself. In practical terms, Korea shouldn't wave this off as someone else's story while reworking its own duty-free system — it's a cautionary tale worth keeping close.