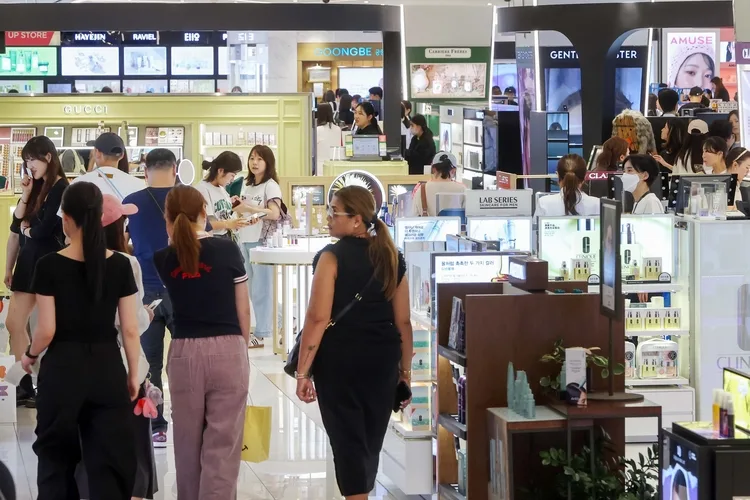
On July 9, the Korea Duty Free Association released May duty-free performance figures. Total sales came to KRW 1.1117 trillion — practically identical to April's KRW 1.1119 trillion. Yet in that same May, inbound foreign arrivals reached 1,945,809, up 19.4% year over year and equal to 131% of May 2019's pre-pandemic level. Tourists are pouring in at record levels, so why has duty-free revenue gone nowhere? Answer that question with "exchange rates" or "weaker spending" alone, and you miss the real story. Laid across the Association's monthly data as a time series, what sits underneath the "stalled" headline is Korea's duty-free demand structure quietly being rebuilt from the ground up.
The May Numbers — What Stalled and What Moved
Here are the facts from this release, first.
- Total sales: KRW 1.1117 trillion (flat versus April)
- Foreign shoppers: KRW 857.0 billion in sales (down slightly month over month) / 1,229,264 buyers (up)
- Domestic shoppers: KRW 254.6 billion in sales (up) / 1,389,530 buyers (up slightly)
- Total buyers: 2,618,794 (+1.8% year over year)
- Inbound visitors: 1,945,809 (+19.4%, 131.0% of May 2019) — China 564,000, Japan 358,000, Taiwan 192,000, U.S. 152,000
Two things already diverge here. Among foreign shoppers, buyer count rose while sales fell; among domestic shoppers, both buyer count and sales rose together. The Association pointed to exchange rates (a dollar-payment-centered structure under a weaker won) and diversifying spending channels as the reasons behind the foreign sales decline. That's an accurate explanation, but only half of one. What matters more is that "how much each person spends" has changed.
Backing out per-person spend from the Association's data, May's average spend per foreign shopper comes to roughly KRW 700,000, and roughly KRW 180,000 for domestic shoppers. By industry tallies, average spend per foreign shopper has fallen by more than KRW 200,000 over the past year. More people are arriving, but each wallet is thinner — that is the substance behind the paradox of "arrivals up 131%, sales flat."
Key Insight #1 — "Flat" Isn't Collapse. It's the Mark Left by a Healthier Market
To read these numbers correctly, you first have to accept that 2019 itself was, in fact, a bubble.
From KRW 24.8 Trillion to KRW 12.5 Trillion — What Actually Halved the Market
Korea's duty-free market peaked at KRW 24.8 trillion in 2019, then roughly halved to KRW 12.5 trillion by 2025 over seven years. The usual explanation points to COVID and the decline in Chinese group tourism. But the real force that inflated 2019's KRW 24.8 trillion wasn't tourists at all — it was daigou (代購), Chinese resellers buying in bulk to resell back home.
Daigou were a wholesale channel: they swept up luxury goods and cosmetics in bulk at downtown duty-free stores and resold them in China. To keep them coming, duty-free operators funneled a large share of that revenue back out as "referral commissions." Sales on the books grew, but almost nothing was actually retained. Once operators began pulling out of that commission-driven bidding war after 2023, daigou-driven sales collapsed, and headline revenue was cut in half.
In other words, a large share of the drop from KRW 24.8 trillion to KRW 12.5 trillion wasn't a collapse in demand — it was the clearing-out of revenue that was never really kept in the first place. Today's monthly revenue in the low-KRW-1-trillion range is what's left once daigou is stripped out — a figure much closer to real, substantive demand.
Seen this way, May's "flat" reads differently. It's the first phase of a market that has taken daigou wholesale off life support and started breathing through its real lungs — individual travelers (FIT) and domestic shoppers. Headline growth has stalled, but the quality of that revenue is actually improving.
Key Insight #2 — Domestic Shoppers Return After Six Years: What a 23% Share Means
The number most worth focusing on this May isn't total sales or foreign sales — it's the domestic share. May's KRW 254.6 billion in domestic sales made up roughly 23% of the total. Laid out across the Association's long-run data, the weight of that number becomes clear.
Domestic shoppers' share of sales stood above half, at 55.3%, in 2010, then collapsed to 15.6% by 2019 as daigou and Chinese group tourism swallowed the market. It bottomed out in the single digits during the pandemic years (2020–2022). It then recovered to 19.5% in 2023, into the 20% range in 2024, and now to roughly 23% this May. Domestic shoppers have been steadily returning to duty free over the course of six years.
Why does this matter? Domestic shoppers don't demand referral commissions the way daigou did. They're also less directly exposed to exchange-rate swings, since their purchases aren't dollar-denominated. In other words, a rising domestic share means a growing share of duty-free revenue is revenue the industry actually gets to keep. Even as the top line looks stalled, the profitability base underneath it is getting sturdier.
Key Insight #3 — From Bulk Luxury Buying to K-Beauty FIT: The Texture of Demand Has Changed
Breaking down individual operators' performance during the "golden week" in early May — when Korean, Chinese, and Japanese holidays overlapped — makes clear how the character of demand is shifting.
- Lotte Duty Free: Total sales up 43% for May 1–5, foreign sales up 46%, domestic sales up 36%. Notably, sales to individual Chinese travelers (FIT) rose 111%. Net sales to individual travelers by nationality also diversified sharply — China +68%, Taiwan +38%, Vietnam +255% — spreading out what used to be a heavily China-concentrated risk
- Shilla Duty Free: Shilla didn't disclose separate daily golden-week figures, but its numbers tell this story most clearly of all. Q1 revenue of KRW 884.6 billion (+7%) with operating profit of KRW 12.2 billion marked a return to profit after seven straight quarters in the red. That came after CEO Lee Boo-jin invested roughly KRW 20.0 billion to strip out the company's dependence on daigou and rebuild the business around FIT, K-beauty, and experiential content — exemplified by makeup-artist beauty classes at the Seoul store's Prestige Lounge and K-beauty experiential promotions such as Medicube on its online store
- Shinsegae Duty Free: Foreign FIT sales grew in the 20%-plus range, with beauty-category sales up 160%. Daily foreign sales for some brands rose as much as 8x (17x at the Myeongdong store, 7x online)
- Hyundai Duty Free: Foreign sales up 77.1%
Two keywords run through all of this: FIT (individual travelers) and K-beauty. Spending built around getting off a tour bus and sweeping up luxury goods along a guide-scripted route is fading, and taking its place is spending where travelers research brands on social media beforehand and pick out K-beauty and K-content products that suit their own taste. The drop in average spend is the inevitable consequence of that shift — the center of gravity has moved from bulk luxury buying (high ticket size) to value-conscious, experiential individual purchases (lower ticket size, higher frequency). Shilla's case in particular proves that this shift isn't a simple cyclical rebound — it's a deliberate restructuring that trimmed away daigou and moved onto individual demand instead.
This dovetails exactly with the "efficiency paradox" in global travel retail that we recently examined in our piece on the Gen Z–Millennial duty-free spending divide. The same phenomenon playing out at airports worldwide — passenger volume rising while per-person spend stalls — is showing up at Korea's downtown and airport duty-free stores in the form of "arrivals up 131%, sales flat."
Business Impact — "Recession-Era Profitability" and the Fork in Operators' Roads
With demand quality improving while the top line stays flat, operator profit and loss now come down to how much fat each has trimmed. The 2025 scorecard makes this plain.
- Hotel Lotte (Lotte Duty Free): Returned to profit through cost restructuring, posting roughly KRW 51.8 billion in operating profit in 2025
- Hotel Shilla (Shilla Duty Free): Posted an operating loss of roughly KRW 50.0 billion in its duty-free division in 2025, but — as shown above — returned to profit with KRW 12.2 billion in Q1 2026 through the same kind of restructuring
In the same market, one operator turned profitable earlier (Lotte), the other later (Shilla). The difference came down not to revenue but to cost control and channel mix, and both companies converged on the same direction: cutting back daigou wholesale and shifting toward individual demand and higher-margin channels. The industry as a whole is holding on by trimming headcount — Shilla's duty-free workforce fell from 811 in 2022 to 645 in 2025, and Hotel Lotte's from 923 in 2023 to 754 in 2025. The era of chasing revenue is over, and the industry has moved into an era of relearning how to actually keep what it earns. That is the substance of what might be called "recession-era profitability." In RIT's view, it's still too early to be purely optimistic about this trend — with the top line stuck at KRW 12.5 trillion, both new hiring and brand recruitment are bound to keep shrinking. The real question is how to turn this "high-quality stagnation" into the next stage of growth, not how to redraw the revenue curve of the KRW 24 trillion era.
✦RIT's Insights
Read the monthly duty-free sales release as a single top-line number, and it always produces the same conclusion: crisis. But from the vantage point of someone who has watched this industry on the ground for more than twenty years, May's numbers actually read as good news. A domestic share climbing to 23% means the era of clinging to daigou revenue that was never really kept in the first place is genuinely coming to an end. For this restructuring to actually show up in the bottom line, though, execution on the ground has to follow. Duty-free merchandising and buying teams need to rebuild their KPIs around post-commission real margin and domestic/FIT sales share, not total revenue. In a market with daigou wholesale stripped out, it isn't how full the shelves are with luxury goods that decides profit and loss — it's the turnover of categories that FIT travelers actually pick up, like K-beauty, K-food, and niche fragrance.
There's a lot of hand-wringing about falling average spend per customer, but RIT sees this as normalization. It was never healthy for one person to sweep up millions of won in luxury goods in one visit — it's healthier retail when several people are instead buying the K-beauty products that fit their own taste. The problem is that assortment and marketing still haven't moved on from the group-tour era to actually capture this individual demand. From a marketing and CRM standpoint, the answer is already sitting in the golden-week data: numbers like Chinese FIT +111% and beauty +160% are a signal to shift budget away from group-tour acquisition and toward social-media-driven individual traveler targeting. If a brand isn't visible before the visit, shoppers won't open their wallets once they're actually in the store. And the domestic shoppers who have returned after six years are one of the few genuinely profitable customer segments left — untouched by exchange-rate pressure and commission costs. Building out pre-departure reservation and pickup services and membership programs aimed at outbound travelers now is, from a retention standpoint, money well spent.
The question the duty-free industry should be asking right now isn't "how do we get revenue back to KRW 24 trillion" — it's "how do we turn KRW 12 trillion into a KRW 12 trillion we actually keep." Get the direction wrong, and the industry repeats its old mistake of bleeding out on commissions just to inflate the top line again. In RIT's view, this point deserves a closer look: as the diverging paths of Shilla and Lotte show, the contest right now isn't decided by revenue growth but by how fast fixed costs and referral commissions get restructured. Corporate planning and finance teams should treat the pace of Incheon Airport lease renegotiations and downtown-store efficiency gains as the real variable that will decide next quarter's results. The same goes for policy. Leaving in place a structure where a 131% recovery in arrivals still doesn't translate into revenue only locks in the industry's contraction — which is why discussions that would actually grow real demand, such as raising the domestic duty-free purchase limit or easing downtown duty-free regulation, are needed.
Sources