Musinsa's Revenue Hit a Record High — So Why Did Consolidated Operating Profit Fall?
2026-08-31 10:47 PMFashion & Luxury
Overview
Musinsa posted record first-half consolidated revenue of KRW 821.7 billion in 2026, but consolidated operating profit fell 11.2% and the company logged a net loss of KRW 15.6 billion. Musinsa cited rising costs and SG&A, plus upfront investment in its global business, as the backdrop for the profit decline. Standalone operating profit grew 13.1% too, yet the operating margin — by back-calculation — slipped from 9.6% to 8.4%. This piece examines the crack that opened up between consolidated and standalone results, and between growth and profitability.
Musinsa's first-half 2026 results, announced on August 31, don't reduce to a single clean sentence. Consolidated revenue came in at KRW 821.7 billion, up 22.5% year-over-year from KRW 670.5 billion — a first-half record. Yet in the same period, consolidated operating profit fell 11.2% to KRW 52.3 billion, and the company posted a net loss of KRW 15.6 billion. Revenue hit an all-time high while profit moved backward. In an August 25 piece covering Musinsa's three-year track record and the gap in its IPO valuation, RIT noted the accounting illusion behind 2025's results: operating profit hit a record KRW 140.5 billion, yet net profit still fell 41%. A half-year later, that pattern has moved a step further — net profit didn't just shrink, it flipped to a loss outright, and this time consolidated operating profit itself moved backward too.
What Happened — Record Revenue, Falling Profit
Even in the second quarter — typically the fashion industry's off-season — consolidated revenue rose 21.3% year-over-year to KRW 458.1 billion. Standalone revenue, which reflects Musinsa's own corporate performance, grew even faster than the consolidated figure: KRW 784.7 billion (+30.0%) for the half, or KRW 449.7 billion (+34%) for Q2 alone.
Profitability is where things get complicated. Consolidated operating profit fell 11.2% to KRW 52.3 billion. The company attributed this to rising costs for raw materials and processing fees, layered on top of higher SG&A — shipping and payment fees in particular — as transaction volume expanded. Standalone operating profit, by contrast, rose 13.1% to KRW 65.7 billion — though that still fell well short of the 30.0% standalone revenue growth. The KRW 15.6 billion net loss shouldn't be read as a straightforward sign of weakening cash generation, either. The company explained that this reflects book-entry interest expense from classifying its RCPS (redeemable convertible preferred stock) as a liability, and that the charge has no bearing on actual cash outflow. Still, gauging Musinsa's true cash-generating capacity would require looking at operating and investing cash flow together.
Metric
H1 2026
YoY
Consolidated revenue
KRW 821.7B
+22.5% (record)
Standalone revenue
KRW 784.7B
+30.0%
Consolidated operating profit
KRW 52.3B
-11.2%
Standalone operating profit
KRW 65.7B
+13.1%
Net loss
KRW 15.6B
Swung to loss
In absolute terms, standalone operating profit grew 13.1% — but the operating margin tells a different story. Standalone revenue of KRW 784.7 billion against operating profit of KRW 65.7 billion works out to a margin of 8.4%. Back-calculating the prior-year period from the disclosed growth rates implies roughly KRW 603.6 billion in revenue and KRW 58.1 billion in operating profit, for a margin of about 9.6% — this isn't a figure the company disclosed directly, but a simple back-calculation from the announced growth rates, so rounding may make it differ from the actual financial statements. By this math, standalone profit grew in absolute size, but the margin slipped from 9.6% to about 8.4%, a decline of roughly 1.2 percentage points. In other words, revenue outran profit. The gap is wider on a consolidated basis — the consolidated operating margin, calculated the same way, fell from 8.8% to 6.4%, a drop of about 2.4 percentage points, nearly double the standalone decline of 1.2 points.
The Key Insight — Where Consolidated and Standalone Diverge, and Why It's Hard to Draw a Firm Conclusion
What this math shows, at its core, is that profit failed to keep pace with revenue growth on both a standalone and consolidated basis. But the profitability decline was larger at the consolidated level. That points to the possibility of additional profit pressure across the broader corporate structure — subsidiaries, overseas units, and consolidation adjustments — not just rising costs at the parent entity itself.
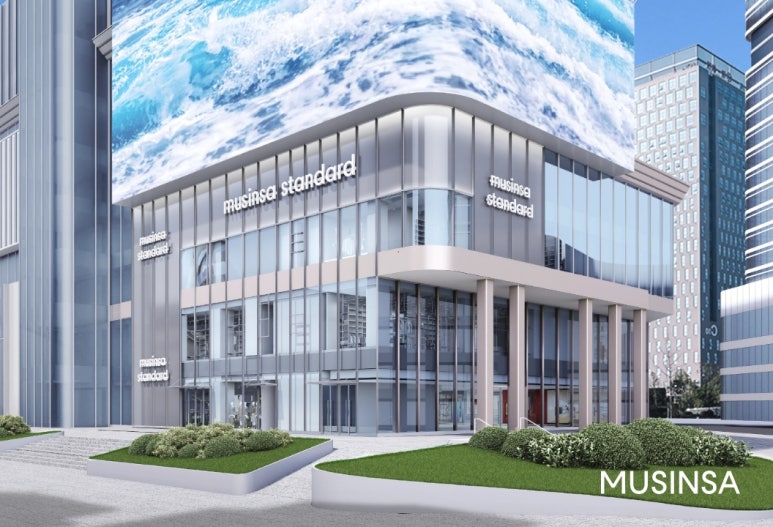
Separate from the profitability question, one thing is clear: Musinsa expanded fast this half. In Q2 alone, the company opened 12 new offline stores — 10 domestic and 2 overseas. In China, it opened Musinsa Standard stores at Xinbaili YOUNG in Shanghai and Hangrong Plaza in Hangzhou. Musinsa Global Store, which operates across 13 regions, saw Q2 transaction value jump more than 143%, and first-half exports rose more than ninefold year-over-year to roughly KRW 37.2 billion.
Musinsa opened stores in Shanghai and Hangzhou in Q2, formally kicking off its offline push into China. New store openings, setting up overseas subsidiaries, and local inventory and staffing all book as costs upfront, while their contribution to revenue and profit shows up only with a lag. What strikes me here is that it's too early to draw a conclusion from a single half's numbers alone — if expansion investment is the main driver of the profitability decline, that may not be a bad sign at all, but confirming that requires watching whether the consolidated operating margin rebounds over the next several quarters. Even so, in absolute terms, Musinsa still posted first-half consolidated operating profit of KRW 52.3 billion and remained profitable. That said, judging the quality of this growth requires weighing not just competitors' margins but profitability relative to transaction value, the share of direct-purchase merchandise, and the scale of offline investment.
Business Impact — The Numbers Behind the Speed of Expansion
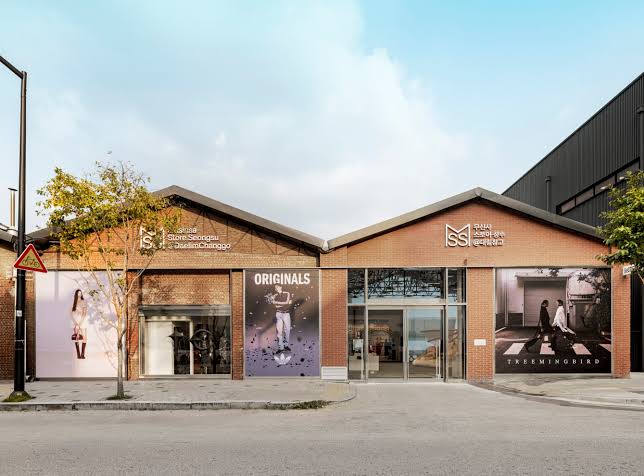
The concrete results behind this half's offline and overseas expansion are striking. Sales at Musinsa's 41 domestic Musinsa Standard stores grew 64% year-over-year in Q2, with foot traffic up more than 66% and surpassing 10 million visitors in a single quarter for the first time. Musinsa Megastore Seongsu, which opened in April, racked up roughly KRW 10 billion in cumulative sales within 68 days of opening, with foreign customers accounting for about 44% of Q2 sales. That said, a sales figure like this doesn't equal profitability. New flagship stores typically carry heavy interior, marketing, and staffing costs in their early months, and since Musinsa hasn't disclosed Seongsu's investment cost or store-level profit and loss, it's hard to judge its profit contribution from the sales figure alone. Musinsa Kicks, the sneaker specialty store, passed 1 million cumulative visitors eight months after opening, with foreign customers accounting for 70% of sales — showing that, at least at its flagship Seongsu and Hongdae locations, foreign tourist demand has become a meaningful pillar of revenue. 29CM, Musinsa's women's fashion and lifestyle platform, broadened into women's designer brands, home and living, and kids categories, and passed KRW 1 trillion in annual transaction value in mid-August.
Overseas, transaction value more than doubled in Taiwan, Thailand, Vietnam, and Indonesia, and starting in July, Musinsa signed a string of partnerships with major Southeast Asian markets including Malaysia, Vietnam, Indonesia, and the Philippines. The expansion pace carries into the second half. Musinsa plans standalone beauty stores of roughly 1,320 square meters each in Hongdae and Seongsu, Seoul, in September and November, and will open Musinsa Standard and Musinsa Beauty stores simultaneously in Jeju in the fourth quarter. Overseas, it will run a large pop-up store featuring more than 80 K-fashion and K-beauty brands in Osaka, Japan in October, and plans to open a Musinsa Store and Musinsa Standard in Shenzhen, China.
From where I sit, the expansion Musinsa is running right now isn't concentrated in any single channel — it's a multi-front push spanning domestic offline retail, China, Southeast Asia, and Japan simultaneously. Given the pace of this simultaneous expansion, some near-term pressure on consolidated operating profit is a plausible explanation, though the detailed profit-and-loss breakdown needed to confirm it hasn't been disclosed. For a company preparing to go public, what investors watch isn't how big revenue got, but how well that growth converts into profit — the quality of growth. In that sense, this half's results are not a light signal for Musinsa as it prepares for its IPO. As RIT noted in the earlier piece, some media outlets and investment-banking circles have reported that Musinsa hopes for a valuation around KRW 10 trillion, while parts of the market have floated a figure closer to KRW 4-5 trillion. This half's numbers — the drop in consolidated operating profit, the swing to a net loss, and the standalone margin decline — add one more unwelcome variable for a company trying to close that valuation gap.
✦RIT's Insights
It's too early to call Musinsa's expansion a success or an overreach based on this one set of results alone. Sales and transaction value are growing fast in both its offline and overseas businesses, but how much cost that growth is being built on hasn't been disclosed. What's clear right now is simply that profit isn't keeping pace with revenue growth.
The KRW 15.6 billion net loss reflects the impact of non-cash RCPS-related expenses, as the company explained. It shouldn't be read as cash outflow or weakening cash generation of the same magnitude. Still, a recurring net-loss figure while preparing for an IPO leaves Musinsa with the ongoing burden of explaining the gap between earnings and cash flow to investors, again and again.
There are three metrics RIT wants to see in the next earnings report. First, whether the consolidated operating margin rebounds from 6.4%. Second, whether the standalone margin's decline stops. Third, whether new offline stores and overseas units start contributing to actual operating profit, not just top-line growth.
If these three indicators improve, this half's profitability decline can be read as the cost of upfront investment for growth. If margin decline continues despite rising revenue, though, it's worth examining whether Musinsa is locked into a structure that requires ever more spending just to sustain its current growth rate. The next few quarters will be the test that decides whether Musinsa's expansion was investment or overreach.