Amorepacific: Overseas Drove Revenue and Domestic Drove Profit in Q1 — Q2 Flipped It
2026-07-24 9:01 PMCosmetics & Perfumes
Overview
In Amorepacific's Q1, overseas revenue grew even as overseas operating profit fell 18%, with profit coming from domestic (+65%). Then the confirmed Q2 results showed the exact opposite picture — overseas operating profit surged 99%, growing faster than domestic (+48%). The hypothesis that Q1's overseas weakness was a one-off cost issue was confirmed by the numbers just one quarter later.
"China's out, the US and Europe are up," "COSRX takes flight overseas" — recent headlines covering Amorepacific's earnings all credit overseas expansion as the success factor. That's not wrong. Revenue in North America, Japan, and Europe did grow sharply. But look closely at the profit line of the actual earnings report and a completely different picture appears. Overseas operating profit actually fell 18%, and most of the profit growth came from the domestic business, where revenue grew only in the single digits. In other words, the star of revenue and the star of profit are different divisions entirely. On top of that, a quiet signal also surfaced: growth in Amorepacific's domestic duty-free channel has slipped below the growth rate of purely domestic channels. This piece first works from Amorepacific Group's officially confirmed Q1 2026 (January–March) results to unpack these two dynamics hiding behind the headlines. It then follows through to the subsequently confirmed Q2 (April–June) results — including the fact that overseas profit flipped to run in exactly the opposite direction.
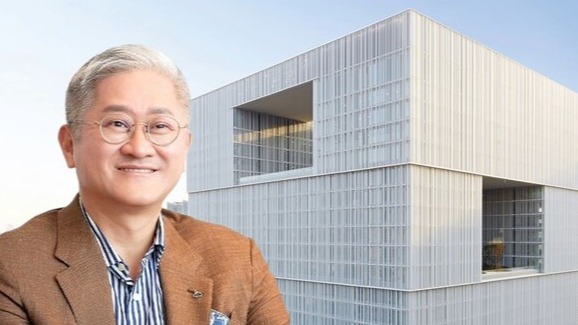
Amorepacific's new Yongsan headquarters — the real driver behind this quarter's earnings wasn't overseas, but the domestic business inside this building
What Happened — Confirmed Q1 2026 Results
Amorepacific Group announced its Q1 2026 (January–March) results on April 29.
Category
Revenue
Operating Profit
Group total (holding company, consolidated)
KRW 1.2227 trillion (+5.0%)
KRW 137.8 billion (+6.9%)
Breaking out the core subsidiary, Amorepacific Corporation (090430), into domestic and overseas:
Category
Revenue
Revenue Change
Operating Profit
Operating Profit Change
Total
KRW 1.1358 trillion
+6%
KRW 126.7 billion
+8%
Domestic
KRW 626.4 billion
+9%
KRW 81.5 billion
+65%
Overseas
KRW 497.1 billion
+6%
KRW 56.7 billion
-18%
Line the numbers up and something odd shows up. Revenue growth was higher domestically (+9%) than overseas (+6%), yet operating profit growth ran exactly the opposite way — overwhelmingly larger domestically (+65%) while overseas profit actually fell (-18%). The intuitive picture would have profit grow faster wherever revenue grew faster, and slower where revenue growth was weaker. This quarter moved in the opposite direction.
Core Insight 1 — The "Overseas-Led Growth" Narrative and the Real Source of Profit Don't Match
Overseas revenue clearly did grow. In North America, COSRX and Estra both posted triple-digit growth; in Japan, Laneige, Hera, Estra, and COSRX all grew strongly together. In Europe, the Middle East, and Africa (EMEA), Estra newly entered 17 countries, and Sulwhasoo and Laneige entered the new markets of EMEA and Japan through the travel retail (duty-free) channel. On the surface, it's exactly the overseas-expansion story it's been made out to be.
But that growth didn't translate into profit. The company hasn't disclosed the specific causes item by item, but the circumstances suggest two factors overlapped. One is Greater China. The China business saw revenue itself decline, attributed to "offline channel efficiency improvements" — and restructuring efforts such as store closures and workforce adjustments typically carry one-off costs. The other is the cost of entering new markets. Simultaneously entering 17 EMEA countries and building out a new travel retail channel requires upfront marketing and distribution investment, with revenue usually following only gradually. The upshot: it's more accurate to describe overseas as a mix of "a growing business" and "a business that hasn't yet turned that growth into profit."
Domestic, by contrast, saw operating profit jump 65% even though revenue growth stayed in the single digits (+9%). By segment, luxury grew 6%, premium grew 20%, and daily beauty grew 12%, with the premium line driving growth — which reads as a shift toward a higher share of high-margin products rather than low-margin volume. The "global expansion drove earnings" media framing holds up on a revenue basis, but on a profit basis, it was actually the improved profitability of the domestic business that contributed far more.
Core Insight 2 — The Duty-Free Channel Is Still Growing, But It's Now Slower Than the "Domestic Average"
Breaking down Amorepacific's domestic channels by revenue growth rate:
Channel
Q1 Revenue Growth
Share of Domestic Revenue
Pure domestic (offline, online, etc.)
+9%
78%
Duty-free / cross-border e-commerce
+8%
22% (of which duty-free alone: 17%)
At a glance, 8% growth in the duty-free/cross-border e-commerce channel doesn't look bad. The company itself described it as "resilient growth." But what's worth noting is that this growth rate is lower than the pure domestic channel's (+9%). The narrative repeated across the K-beauty industry in recent years has been that "a surge of foreign tourists drives duty-free and cross-border e-commerce growth." Yet in the own data of Amorepacific — a company that represents K-beauty — a signal is emerging that the duty-free channel is no longer the fastest-growing part of the domestic business.
This trend connects with data RIT has covered on the Korean duty-free industry more broadly — trade-association statistics showing total duty-free revenue stalling even as inbound foreign tourist arrivals have far surpassed pre-pandemic levels, and figures showing per-capita spending by foreign visitors falling by more than KRW 200,000 in a single year. The growth gap across Amorepacific's channels looks close to corroborating evidence that this industry-wide structural shift is now showing up in individual brand companies' results as well.
Confirmed Q2 Results — Overseas Profit Flipped Exactly in Reverse
On July 30, Amorepacific Group announced its Q2 2026 (April–June) results. The outcome was the exact mirror image of Q1.
Category
Revenue
Operating Profit
Group total (holding company, consolidated)
KRW 1.2543 trillion (+14.6%)
KRW 122.8 billion (+53.3%)
Breaking out the core subsidiary, Amorepacific Corporation, into domestic and overseas:
Category
Revenue
Revenue Change
Operating Profit
Operating Profit Change
Total
KRW 1.1759 trillion
+17%
KRW 117.3 billion
+59%
Domestic
KRW 610.8 billion
+10%
KRW 59.6 billion
+48%
Overseas
KRW 551.6 billion
+28%
KRW 71.8 billion
+99%
In Q1, overseas operating profit fell 18%; in Q2 it surged 99%. Domestic (+48%) still posted a strong result, but this quarter overseas even outpaced domestic in profit growth — exactly the reverse of Q1. By margin, overseas operating margin came to roughly KRW 71.8 billion ÷ KRW 551.6 billion ≈ 13%, staying in double digits, while domestic came to roughly KRW 59.6 billion ÷ KRW 610.8 billion ≈ 9.8%, matching the company's own reference to "about 10%." The company said it achieved a "double-digit operating margin for two straight quarters" — meaning overseas profitability, on a margin basis, was never actually weak, even in Q1. It was specifically the year-over-year growth rate that had been suppressed by one-off factors like Greater China channel restructuring and new-market entry costs — exactly the hypothesis this piece raised after Q1, now confirmed by the numbers.
Actual results also beat brokerage estimates by a wide margin. Back at the Q1 stage, NH Investment & Securities had projected Q2 revenue of KRW 1.0925 trillion and operating profit of KRW 100.0 billion, with market consensus around KRW 97.1 billion in operating profit. The actual results (revenue KRW 1.2543 trillion, operating profit KRW 122.8 billion) beat both estimates by more than 20%.
Not every division did well, though. RIT's concern with these results sits right here — the company's four standalone beauty-brand subsidiaries (Innisfree, Etude, Espoir, and Amos Professional) posted weak results, with revenue down 13% and operating profit down 51%. That's the impact of ongoing distribution-channel streamlining, including road-shop reductions; the company said "the products themselves are growing fine." Greater China revenue also kept declining, again attributed to "channel efficiency improvements" — the same pattern repeating from Q1. In other words, the Q2 turnaround isn't a story of "everything got better." It's that investment in the new markets of North America, EMEA, and Japan started converting into profit, and that effect more than offset the structural weakness at the road-shop brands and in Greater China.
Amorepacific's Q1 results didn't fit neatly into the easy "overseas expansion drove growth" narrative. Revenue's star was overseas, but profit's star was domestic. Then the confirmed Q2 results flipped that picture exactly — overseas operating profit surged 99%, outpacing domestic (+48%), and the results overall beat brokerage estimates by more than 20%. The hypothesis that Q1's overseas profit weakness was a one-off cost issue rather than a structural problem was confirmed by the numbers just one quarter later.
✦RIT's Insights
Had this piece ended with the Q1 numbers alone, it would have read as "Amorepacific is a company whose profit is carried by its domestic business." Exactly one quarter later, the opposite happened. That's the most important lesson in this case — a single quarter's profit direction shouldn't be taken as proof of a company's underlying structure. The hypothesis raised after Q1 — that the overseas profit decline was likely a one-off factor like Greater China channel restructuring or new-market entry costs — was validated precisely by the Q2 numbers, which is a good example of why it matters to dig into the structural "why" behind a quarter's results, not just the direction of the headline number. Anyone on the investment or analyst side should take away one principle from this: don't treat "overseas revenue growth" and "overseas profit growth" as the same thing. As this case shows, revenue and profit can move in opposite directions by region, and flip again by quarter — the two metrics need to be tracked separately.
At the same time, a good Q2 doesn't mean every problem disappeared. The weakness at the four brand subsidiaries — Innisfree, Etude, Espoir, and Amos Professional (revenue -13%, operating profit -51%) — and the Greater China revenue decline repeated in Q2 exactly as they had in Q1. The rapid growth of new overseas markets (North America, EMEA, Japan) is simply masking that weakness for now; the structural issues at the road-shop-centered brands and in the China market haven't actually been resolved. It's important not to miss the still-weak divisions sitting behind a good headline number. Anyone handling brand or channel strategy should take from this case that a lag between revenue growth and profit growth is natural in the early stages of entering a new market — Amorepacific's overseas profit swung from -18% to +99% in a single quarter. That said, the weakness at road-shop-centered brand subsidiaries like Innisfree and Etude has now run for two straight quarters, so "temporary lag" and "structural decline" shouldn't be lumped together.
The signal that duty-free channel growth has slipped below the pure domestic channel's growth rate also remains valid. The K-beauty industry has more or less automatically equated rising tourist arrivals with rising duty-free revenue — and the fact that this link is loosening even in the channel data of a company that represents the industry means it's time for both duty-free operators and the brands sold inside their stores to rethink channel strategy. This is exactly where RIT thinks duty-free and travel-retail teams need to be especially careful: now that individual brand-company data confirms rising inbound tourism and duty-free channel growth don't always move in proportion, channel planning needs to be rebuilt around comparing actual growth rates by channel rather than tourist-arrival counts. And for management and IR teams, this case shows directly why building investor materials that clearly explain how group-level and core-subsidiary-level numbers differ — and how domestic and overseas profit can move in opposite directions — is directly tied to managing credibility. Even when results beat market consensus by a wide margin, explaining that certain divisions remain weak makes it easier to manage expectations for the next quarter. Whether this pattern continues into Q3 results is the next thing to watch.
DART electronic disclosure system (dart.fss.or.kr) — Amorepacific and Amorepacific Group's 2026 quarterly reports (cited by name where a specific filing URL could not be pinpointed)