Is the Swiss Watch Industry Bottoming Out? — Exports Fell 0.7% in H1 2026 While Swatch Group Grew 8.5% at Constant Currency
2026-08-28 8:41 AMFashion & Luxury
Overview
Swiss watch exports fell 0.7% year over year in H1 2026 to CHF 12.824 billion, but wristwatch export volume rose 2.3%, and June and July exports grew 11.2% and 9.6% respectively, pushing the January-July cumulative total up 0.9%. Swatch Group, owner of Omega, Tissot and Longines, grew revenue 8.5% at constant currency even as industry exports stagnated, but its operating margin was just 1.7%. The Korean subsidiary grew revenue for a second straight year, yet its net loss widened.
In the first half of 2026, the Swiss watch industry looked less like a full recovery and more like a bottoming-out phase after a downturn. According to the Federation of the Swiss Watch Industry (FH), total watch exports for the half came to CHF 12.824 billion, down 0.7% year over year. Wristwatch export volume, however, rose 2.3%, and June and July exports grew 11.2% and 9.6% respectively, turning the January-July cumulative total positive at +0.9% year over year. It's worth noting that FH's figures track exports shipped out of Switzerland, not final consumer sales.
Swatch Group — owner of Omega, Tissot, Longines, Hamilton, Breguet, Blancpain and Swatch — told a distinctly different story. H1 2026 revenue came to CHF 3.121 billion, up 8.5% at constant currency and 2.0% at actual exchange rates. Q2 growth was 9.4% at constant currency, accelerating to 13.1% in May-June (industry export figures and a single company's revenue aren't measured on the same basis — more on that distinction later in this piece). Operating profit, however, was just CHF 52 million, for an operating margin of 1.7%. Revenue recovered, but a strong Swiss franc, low factory utilization, and the cost of retaining production staff weighed on profitability.
In Korea, Swatch Group Korea's revenue grew for a second straight year after a sharp drop in 2023 — but profitability turned into a net loss. According to a corporate-information service citing NICE D&B audit data, 2025 revenue rose 6.0% to roughly KRW 348.1 billion, while net loss came to roughly KRW 6.9 billion (a separate corporate-information service puts the operating loss at roughly KRW 5.6 billion). The global group's reported 12% growth in Korean revenue and the Korean subsidiary's own 6.0% growth rate shouldn't be read as the same metric — currency effects, differences in scope, and different revenue-recognition standards can explain the gap.
Swiss Watch Exports Fell 0.7% to CHF 12.8 Billion in H1 2026
The Swiss watch industry exports roughly 95% of its production to about 200 markets worldwide, making it one of the country's most export-dependent sectors. That leaves it directly exposed not just to global consumer spending, but to the Swiss franc exchange rate, US tariff policy, the Chinese economy, Middle East geopolitics, and retailer inventory levels around the world. In H1 2026, uncertainty around US tariffs, geopolitical conflict in the Middle East, a strong franc, and rising gold prices all weighed on the industry at once.
Omega, Tissot, Longines, Breguet, Blancpain and the other brands under Swatch Group
FH's tally for total Swiss watch-related exports in H1 2026 came to CHF 12.824 billion, down 0.7% from CHF 12.9159 billion a year earlier. Wristwatch exports specifically came to CHF 12.2385 billion, down 0.6%. Wristwatch export volume, however, rose 2.3% to roughly 7.139 million units — more units shipped, but a slightly lower total export value.
Figures in Swiss francs (wristwatch export volume excluded)
Swiss watch exports
H1 2025
H1 2026
Change
Total watch industry exports
CHF 12.9159B
CHF 12.824B
-0.7%
Wristwatch exports
CHF 12.3151B
CHF 12.2385B
-0.6%
Wristwatch export volume
6.977 million units
7.139 million units
+2.3%
Movement exports
CHF 78.7M
CHF 72.9M
-7.4%
Movement export volume
1.334 million units
1.196 million units
-10.3%
FH's figures are based on export prices and shipment volumes declared to Swiss customs, and differ from final consumer sales figures.
FH's price-tier and material breakdowns make the source of the volume increase clearer. Most of the H1 volume growth came from mechanical watches priced under CHF 500 — export volume in that tier rose 23.8%. On the value side, a 5.7% drop in exports in the CHF 500-3,000 tier worked against the total. By material, precious-metal watch exports fell 6.5%, while bimetal watches rose 20.0% and other-metal watches rose 14.4% (steel watches fell 6.5%). The volume increase is real, but it's more accurate to read it as strong shipments in specific accessible price tiers and materials, rather than a blanket claim that "consumers shifted to cheaper watches."
Industry momentum also varied sharply by quarter and by month. According to outside analysis, cumulative Q1 2026 exports were up about 1.4% year over year, but April saw a 16.6% drop, and May grew just 0.4%. FH's official tally shows June exports of roughly CHF 2.4 billion, up 11.2%, and July exports of CHF 2.6283 billion, up 9.6%. That pushed the January-July cumulative export total up 0.9% year over year, turning it positive. Looking at H1 (January-June) alone, the picture is close to stagnant, but the month-by-month pattern from May onward shows signs of a turn.
Still, it's too early to call the June rebound a full industry-wide recovery. FH noted that exports to France rose 63.4% in H1, but attributed this to a shift in logistics routing — goods re-exported to other European countries through France — rather than genuine French consumer demand. A separate outside analysis estimated that excluding this one-off effect would lower June's growth rate to around 5.6%, though that figure is an external estimate, not an official FH adjustment. FH itself forecast that full-year 2026 results would land roughly in line with the prior year, while flagging very high uncertainty tied to future US tariffs and the situation in the Middle East.
China's Drag Has Eased, but the US and Middle East Remain Wild Cards
The Swiss watch industry's biggest structural burden has been the China market. Combined exports to mainland China and Hong Kong fell roughly 30% over the preceding two years. The decline eased somewhat in H1 2026 — FH's figures show mainland China exports down 5.0% while Hong Kong rose 3.3%, leaving Greater China roughly flat overall. Mainland China ranked as Switzerland's second-largest watch export market at the end of 2024, but had fallen to sixth place by H1 2026. The decline has clearly slowed, but that's a different claim from saying China has returned to being a growth engine.
The US remains the Swiss watch industry's largest market, but H1 2026 exports there fell 14.8% year over year. Much of that reflects a high base effect — shipments were front-loaded ahead of tariffs taking effect in Q2 2025 — and compared with H1 2024, US exports were actually up 2.6%. On top of that, a weaker dollar against a stronger franc has squeezed both the price competitiveness of Swiss watches in the US market and exporters' margins.
The Middle East accounts for roughly 10% of Swiss watch exports, but total exports to the region fell 2.0% in H1 2026 — though the UAE, its largest market there, grew 1.6%. Regional conflict since late February 2026 appears to have added uncertainty to distribution and tourism-driven spending. By contrast, emerging markets like Mexico (+14.9%) and India (+31.5%) grew strongly. China's shrinking share is real, and emerging markets are broadening the demand base, but it's worth being clear that not every alternative market — the US and Middle East included — grew at the same time.
Swatch Group Grew 8.5% While Industry Exports Fell
Swatch Group's H1 2026 diverged sharply from the industry average. Group net sales came to CHF 3.121 billion, up 2.0% at actual exchange rates from CHF 3.059 billion a year earlier. At constant currency, growth was 8.5%. A negative currency effect of roughly CHF 200 million shaved about 6.5 percentage points off the reported growth rate. As noted above, FH's industry export statistics and Swatch Group's company revenue are measured on different bases, so the two growth rates shouldn't be compared directly as the same metric.
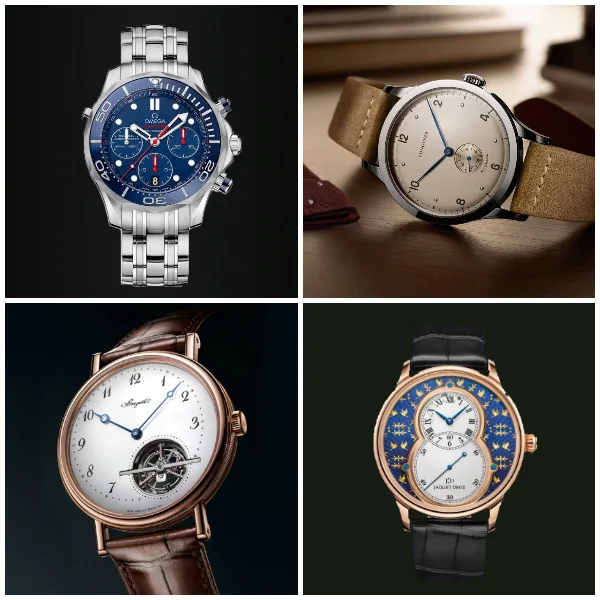
An Omega diver's watch, a Longines dress watch, a Breguet tourbillon, a Jaquet Droz art dial — products from Swatch Group's family of brands
Swatch Group
H1 2025
H1 2026
Change
Net sales
CHF 3.059B
CHF 3.121B
Actual +2.0%, constant currency +8.5%
Q2 revenue growth
—
—
Constant currency +9.4%
Operating profit
CHF 68M
CHF 52M
About -24%
Operating margin
2.2%
1.7%
-0.5pp
Operating cash flow
—
CHF 304M
+68.9%
Net liquidity
—
CHF 1.125B
—
Equity ratio
—
85.3%
—
Figures in Swiss francs (percentage rows excluded). Based on Swatch Group's own press-release figures; H1 2026 net profit was CHF 16 million (no comparable prior-year figure was confirmed, so it isn't shown in the table). Some financial-data services report different figures, likely due to differences in account classification or data conversion, so this piece uses the company's own reported figures throughout.
Growth accelerated as the half went on. Q2 revenue grew 9.4% at constant currency, and May-June alone grew 13.1%. Excluding the manufacturing division, the Watches & Jewelry business's H1 revenue grew 9.5% at constant currency with a 9.0% operating margin. According to secondary reporting, that same business's May-June operating margin improved to as high as 15.0%. Separately, the group-wide May-June operating margin that Swatch Group itself disclosed in its official half-year report was 8.6% — the segment-level figure (excluding manufacturing) and the consolidated group figure (including manufacturing) are different numbers and should be read separately. Set against the group's 1.7% cumulative H1 operating margin, it's clear the manufacturing division's weakness weighed heavily on consolidated profitability.
By region, US revenue grew 27%, Spain 28%, and Italy 12%. In Asia-Pacific, Japan grew 20%, Korea 12%, and Australia 5%, while emerging markets showed strong gains — India 38%, Mexico 26%, Saudi Arabia 41%. These are company-level revenue growth figures in local currency or at constant exchange rates, on a different basis and scope from the FH country-level Swiss export figures discussed above.
Brand and channel mix also contributed to growth. Swatch Group's own boutique sales grew 18% on a comparable-store, constant-currency basis, and online sales grew 30%. Omega's own retail sales grew 20%, while Longines, Tissot and Hamilton all posted double-digit growth. Cross-brand collaborations within the group — like MoonSwatch (Omega x Swatch) and the Scuba Fifty Fathoms (Blancpain x Swatch) — stand as a signature example of how Swatch Group has built reach across a broad consumer base. The company cited its diverse brand portfolio, new product launches, and improved retail efficiency as the drivers behind H1 2026 growth.
Revenue Grew, So Why Did Profit Shrink?
Swatch Group's core problem in H1 2026 wasn't demand — it was low utilization in its manufacturing division. Even through the downturn, the group chose to preserve production capacity and its skilled workforce rather than lean on short-time work compensation or large-scale layoffs. With demand not yet fully recovered, the ongoing burden of labor costs and fixed manufacturing expenses kept the manufacturing division in the red, offsetting a substantial share of the profit generated by the watch and jewelry sales business.
A strong Swiss franc was also a drag. Swatch Group's H1 revenue grew 8.5% at constant currency, but just 2.0% at actual exchange rates. The company put the negative currency effect at roughly CHF 200 million. Revenue was hit by roughly CHF 308 million from currency effects in 2025 as well — a sign that currency, not just product demand, has had a significant recent impact on the group's reported revenue and profit.
The same problem showed up in the full-year 2025 results. Swatch Group's 2025 revenue was CHF 6.28 billion, down 1.3% at constant currency and 5.9% at actual exchange rates. Operating profit fell from CHF 304 million in 2024 to CHF 135 million, and the operating margin dropped from 4.5% to 2.1%. Net profit was CHF 25 million, down sharply from CHF 219 million in 2024.
Figures in Swiss francs (percentage rows excluded)
Swatch Group annual results
2024
2025
Net sales
CHF 6.735B
CHF 6.28B
Operating profit
CHF 304M
CHF 135M
Operating margin
4.5%
2.1%
Net profit
CHF 219M
CHF 25M
Net margin
3.3%
0.4%
The 2025 revenue decline of -5.9% is stated on a like-for-like basis excluding the eyewear business (transferred to Rivoli Group as a separate company at the end of 2024). As a result, there's a gap between the roughly -6.8% decline implied by simply comparing the two years' reported absolute revenue figures and the company's own reported -5.9% decline at actual exchange rates.
A shift began in the second half of 2025. H2 revenue grew 4.7% at constant currency, Q4 grew 7.2%, and Watches & Jewelry revenue excluding China, Hong Kong and Macau grew 10.4% in Q4. That momentum carried into H1 2026's 8.5% growth and May-June's 13.1% growth, suggesting the revenue-side recovery has had reasonable continuity. Swatch Group itself forecast that the May-June and early-July sales acceleration would lift factory utilization and meaningfully improve second-half profitability. That, however, is the company's own forecast, premised on continued demand recovery — whether the manufacturing division's losses actually shrink will only be confirmed in the H2 2026 results.
Swatch Group Korea: Revenue Recovered, but Net Losses Continued for a Second Year
Swatch Group Korea is the local entity responsible for domestic distribution, retail and after-sales service for group brands including Omega, Longines, Tissot, Hamilton, Rado, Mido, Breguet, Blancpain, Glashütte Original and Swatch. It's a wholly owned subsidiary of Swatch Group's headquarters, and unlike the global group, it closes its fiscal year in December — so comparing the global group's H1 results with the Korean subsidiary's annual audited figures requires accounting for the different reporting periods.
Combining public corporate data and audit filings, Swatch Group Korea's revenue fell 17.5% from KRW 373.4 billion in 2022 to KRW 307.9 billion in 2023. Operating profit plunged 73.4%, from KRW 52.3 billion to KRW 13.9 billion. In 2024, revenue grew roughly 6.6% to KRW 328.2 billion, but the company swung to an operating loss of KRW 2.6 billion and a net loss of KRW 4.7 billion.
In 2025, revenue grew again, up 6.0% to roughly KRW 348.1 billion. According to a corporate-information service citing NICE D&B audit data, the net loss widened to roughly KRW 6.9 billion from the year before. A different corporate-information service puts the 2025 operating loss at roughly KRW 5.6 billion. Revenue recovered for a second straight year, but the net loss appears to have widened rather than narrowed — though the operating-loss figure specifically would need to be checked against the original audited report filed with Korea's Financial Supervisory Service.
Swatch Group Korea
2022
2023
2024
2025
Revenue
3,734
3,079
3,282
3,481
Operating profit
523
139
-26
-56*
Operating margin
~14.0%
~4.5%
~-0.8%
~-1.6%*
Net profit
377
74
-47
-69
Figures in KRW 100 million (억원) unless noted otherwise.
2022–2024 figures are from public data based on NICE Information Service; 2025 revenue and net loss are from a corporate-information service citing NICE D&B data, rounded to the nearest KRW 100 million. * The 2025 operating loss and operating margin come from a separate corporate-information service and would need to be checked against the original audited report.
One notable wrinkle: the global Swatch Group reported that Korean revenue grew 12% in H1 2026. That figure, however, covers January-June 2026 on a group-consolidated basis — a different period from Swatch Group Korea's 6.0% annual revenue growth for 2025. The global group's Korea revenue figure may also reflect internal management accounting standards, currency adjustments, and direct or indirect brand-level transactions, so it shouldn't be assumed to match the Korean subsidiary's statutory revenue.
Why Swatch Group Outpaced a Stagnant Industry
Swatch Group's strength lies in not concentrating solely on top-tier watches, but holding a broad portfolio spanning entry-level to ultra-high-end. A lineup running from Swatch and Flik Flak through Tissot, Hamilton and Mido, Longines and Rado, Omega, and on to Breguet, Blancpain and Glashütte Original lets the group respond to shifting conditions and consumer segments across different markets. In H1 2026, revenue grew across every price tier and continent, with particularly strong momentum in accessible price points and the group's own retail channels.
Swatch Group itself said it significantly gained global market share in H1. Against a 0.7% drop in industry exports, the group's 8.5% constant-currency revenue growth is a signal that points in that direction. But FH's export statistics and the company's revenue aren't the same metric — FH aggregates customs-declared export values across every Swiss watchmaker, while Swatch Group's revenue is a consolidated accounting figure that includes distribution and consumer sales. So the two published figures alone don't let an outside observer calculate the precise scale of any market-share gain.
Why Didn't Korea's Revenue Growth Translate Into Profit?
2025 revenue of KRW 348.1 billion is still roughly 6.8% below 2022's KRW 373.4 billion. That said, the publicly available summary data doesn't break out enough detail — cost of goods sold, SG&A, inventory valuation, terms of transactions with headquarters — to pin down exactly why the net loss widened even as revenue recovered.
Globally, the group's own boutiques and online sales have grown quickly, but whether Korea saw the same shift in distribution structure, and whether that came with related costs, can't be confirmed from public data. A clearer picture would require checking cost of goods sold, SG&A, related-party transactions, and inventory notes in the original audited report. In RIT's view, the standard for judging the second half is ultimately clear. For the Swiss watch industry as a whole, the key question is whether the revenue recovery translates into higher factory utilization and a better operating margin; narrowed to the Korean subsidiary, the next benchmark is less the revenue growth itself and more whether that growth translates into normalized inventory, more efficient costs, and a return to profit.
✦RIT's Insights
The Swiss watch industry's H1 2026 numbers don't point in a single direction. Export value fell 0.7%, but wristwatch export volume rose 2.3%. Exports collapsed in April, then rebounded sharply in June and July. RIT reads this as a market where recovery speed diverges by price tier, material and region — not a story of high-end watches booming on their own, nor one of the whole industry sinking together. That said, it's still too early to call this half's numbers a "recovery" — mainland China's falling rank among Swiss export destinations, the US's high base effect, and Middle East tensions remain live variables, so whether the June-July rebound holds needs to be reconfirmed against second-half data. It's also worth not missing that the volume increase came mainly from watches priced under CHF 500 (+23.8%). Rather than reading that directly as "consumers shifted to cheaper watches," it's safer to treat it as a directional signal that shipments in that accessible price tier were relatively strong.
Swatch Group leveraged its broad price range and direct distribution network to grow faster than the industry average. But revenue growth and profit recovery are two separate problems. It's fairly clear that fixed costs in the manufacturing division are what's weighing on headquarters' profitability. In RIT's view, the thing to watch in the second half isn't revenue — it's the manufacturing division. Whether the May-June demand acceleration translates into higher factory utilization is the key variable for operating-margin recovery; if demand slows again instead, the strategy of retaining staff could turn into a lingering fixed-cost burden.
The Korean subsidiary, by contrast, saw its net loss widen even as revenue recovered, and the publicly available summary data doesn't make it possible to pin down exactly which factor — cost of goods sold, headquarters trading terms, inventory, or store costs — is driving that deterioration. In practice, this is exactly the kind of situation where it's easy to be reassured by the top-line growth number alone; anyone in Korean retail or distribution assessing Swatch Group Korea's next results should look past the revenue growth rate to gross margin, inventory levels, and whether SG&A and headquarters trading terms are improving together. Heading into the second half of 2026, RIT thinks it's more important to watch whether the global manufacturing division's losses shrink and whether Swatch Group Korea can turn a profit, than to focus on the sales growth rate alone.
Financial Supervisory Service DART electronic disclosure system (dart.fss.or.kr) — Swatch Group Korea Co., Ltd. audit reports for FY2022–2025 (cited by name where a specific filing URL could not be pinpointed)